or
It's happy hour! But the bar is on the Titanic...
TL;DR: The proposed Altersvorsorgedepot ("Riester 2.0") drops the old capital guarantee, finally allowing low-cost ETF investing, and includes significant incentives. But with fees capped at 1.5% p.a., it's not always better than a simple DIY portfolio even with the incentives you get. Read on to see in which cases it does beat a simple, DIY portfolio.
Update, October 2026:
This post was written in February 2026, based on the government’s first draft. The law has since been passed, and several details changed: the allowance is now 50% on the first €360 and 25% up to €1,800 (max. €540/year), the planned increase in 2029 was dropped, the 1% cost cap applies only to the standard depot, and there’s a new €200 bonus for savers under 25. For the current rules, see Coming soon to a broker near you: Riester 2.0. The calculations below have been corrected but still use the draft’s assumptions.
The original "Riester" pension was first introduced in 2002. By now it's safe to say that it failed miserably - high fees and very low returns due to the "guaranteed capital" concept made it an unattractive investment product.
The proposed Altersvorsorgedepot, nicknamed "Riester 2.0", is planned to be launched in 2027 and is meant to address some of those issues:
In short, it's a state-incentivized investment portfolio, allowing savers to waive the 100% capital guarantee, finally unlocking the option to invest in low-cost ETFs and generate significant returns over years of saving and investing.
There's some good in it, some bad, and as always, some complexities.
How will it work and for whom does it make sense? Let's dive in.
The basics
The general idea
Savers will be able to open a designated trading account at one of several approved providers and deposit into that account as they want. Additionally, the state will add incentives on top of the deposited amount, and will grant savers certain tax benefits. The costs of this plan are regulated, but providers are allowed to charge up to 1.5% per year in fees.
How much can you get?
Up to 1,200€/year, you'll get 30 Cents for every Euro. If you invest 1,200€, you get 360€ as a bonus (In 2029 this amount should increase to 35 Cents per Euro).
For the next 600€, from 1,201€ up to 1,800€, you get 20 cents per Euro, so that's another 120€.
In total, if you invest the maximum amount of 1,800€, you'll get a total of 480€ on top of that, making the grand total 2,280 Euro per year.
But wait, there's more: for every child of yours, who's eligible for child allowance (Kindergeld), you'll get an additional bonus of 300€/year.
Additional tax benefits
On top of the incentives, the total invested amounts (your own investments and the state incentives) will be considered as a deductible cost for tax purposes and can be used to reduce your overall tax burden.
If at this point it feels like it's a bit too good to be true, well - listen to your heart. Some hard truths are coming...
The Saving Phase
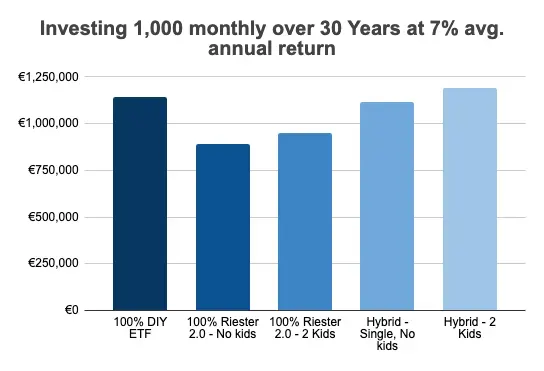
Let’s compare investors saving 1,000€/month over 30 years at a 7% return.
Some points worth mentioning:
- I indeed assumed that from 2029, the base incentive jumps from 30c to 35c per €1 (bringing the first-tier maximum to €420 and the total to €540).
- Child Cap: The €300/child bonus is a great "instant return," but the maximum duration for a child to receive child allowance is 24 years (might be less but I wanted to be optimistic in terms of benefits and incentives). In our 30-year example, I've assumed two kids are born in Year 1. You get the bonus for 24 years, then it vanishes.
- Effective Tax Shield: If you are a high earner (42% bracket), your tax deduction is worth ~€957. BUT: Since the €480 bonus you already received is deducted from that amount, you're left with an effective tax shield of €477. In the calculation below, this amount is reinvested back into the pot.
- Fees: as mentioned above, providers will be allowed to charge "up to" 1.5%. This is pretty much like telling a T-rex it can eat "up to" 10 sheep. I wouldn't expect it to spare any sheep out of kindness, so we have to assume a 1.5% annual fee.
I've looked at a few different alternatives:
- DIY: You invest the entire 1,000€ into a low-cost ETF portfolio
- Riester 2.0: you go all-in on the new Riester plan, up to the cap of €6,840, and the rest into a DIY ETF portfolio.
- Optimized: you deposit into the Riester 2.0 plan the maximum amount that is incentivized, to maximize benefits, and the rest goes into a low-cost ETF portfolio.
Let's see what you'd get in each scenario:
Total amount accumulated at the end of the 30-Year period:
Strategy
Total Value
vs. Pure ETF
100% DIY ETF (0.2% fee)
€1,133,000
Max. Riester 2.0 - No kids (1.5% fee)
€1,074,000
-€59,000
Max. Riester 2.0 - 2 kids (1.5% fee)
€1,112,000
-€21,000
Optimized - Single, No kids
€1,174,000
+€41,000
Optimized - 2 kids
€1,212,000
+€79,000
Optimized Strategy: Investing only up to the subsidized limit (~€1,800 + bonuses) in the Depot; the rest in a low-cost broker.
For a single with no kids, maxing out the Riester 2.0 plan means paying around €91,000 in fees, and ending up almost €60,000 behind a simple ETF portfolio.
The Real Tax Benefit (and why it’s a loan, not a gift)
Like every other private long-term saving product in Germany, one of its key selling points is tax savings in one way or another. Here as well, if you're earning well, you'll love the Sonderausgabenabzug (special expense deduction). This is how it works:
As already mentioned above, the real tax saving is not 957€, but rather 957-480=477. However, never forget: this is a tax-deferred product. You save taxes at 42% today, but you will pay your full personal income tax rate on every single Euro (principal + all gains) when you withdraw it. In a private ETF, you only pay 18.46% tax on the gains.
The Payout Phase: Freedom vs. "The Factor"
Accumulating the money is only half the battle. The real "hidden fee" appears when you try to spend it.
The DIY ETF Portfolio (The "3.5% Rule")
- Withdrawal: In my calculation, I assumed you can withdraw 3.5% of your total portfolio value in the first year and then adjust it for inflation. It's basically a more conservative version of the more well-known 4% rule. In our case, you withdraw €40,075 before tax.
- Taxation: You pay a flat 18.46% effective tax on profits only.
- Flexibility and full control: You own the shares. You decide. If you want to increase/decrease the withdrawals, permanently or just once, you can. If you pass away, your family inherits the full balance.
The Altersvorsorgedepot (The "Rentenfaktor" Trap)
- The Factor: Providers use a Rentenfaktor to calculate your monthly payout. Because they have to insure themselves against you living to 120, they often pay out the equivalent of only 2.5% to 3% (or lower), significantly lower than the DIY rate.
- Full Taxation: Your monthly allowance is taxed as full income. If you have a decent state pension, rental income or any other income source, your tax rate on these withdrawals will be much higher than 18.46%.
- The "Exit" Tax: While not all details have been finalized, looking at other similar incentives, it's reasonable to expect that if you move outside the EU (USA, UK, Switzerland), you'll be required to repay all bonuses and tax breaks in one lump sum.
Final Verdict
When comparing the new Riester 2.0 to a simple, low-cost ETF portfolio, we did see one scenario where this would make sense; the Optimized Strategy. Even then, that is only true if:
- You stop exactly at the cap. Investing anything above the incentivized amount into a product with a 1.5% fee simply doesn't make sense.
- You are staying in Germany. Plans change, life happens. To be heavily "fined" for moving away is not something anyone would choose to add to the mix.
And so we end up with a product which, the best that can be said about it is that, under certain circumstances, it's not terrible.
What would have made it great? First and foremost, lower fees. Simple as that. 1.5% is A LOT. In the last year of our example, the fee on the Riester plan would be around €7,800, more than the €6,840 you deposit into it that year. 7,800€, for "managing" a simple ETF portfolio.
But to me, there's a bigger question: Is the proposed Riester 2.0 a real change in the German pension landscape? Unfortunately, my answer would be no. It's not.
The only case where it makes clear sense is in combination with a simple, independent investment into a low-cost ETF portfolio. But for anyone who's capable of doing that, this doesn't solve any real problem. It simply ties them down to an expensive product, which serves more as a "loyalty program" to Germany itself, than a real, tax-optimized, simplified long-term investing product.
And another thing: it's nice to compare scenarios and run calculations, but zoom out for a moment and consider the actual amounts: the fully incentivized amount is 1,800€ PER YEAR. With the added incentives, even with 3 kids, we're still in the 3,000 region. This is a very low amount. Alone, this amount will not solve anyone's pension problem.
A real change in the system, a true revolution, will only come when the default plan is built so that in most reasonable scenarios it can provide a good standard of living for a person who worked their entire life and contributed into the system. Riester 2.0 is very, very far away from that.